


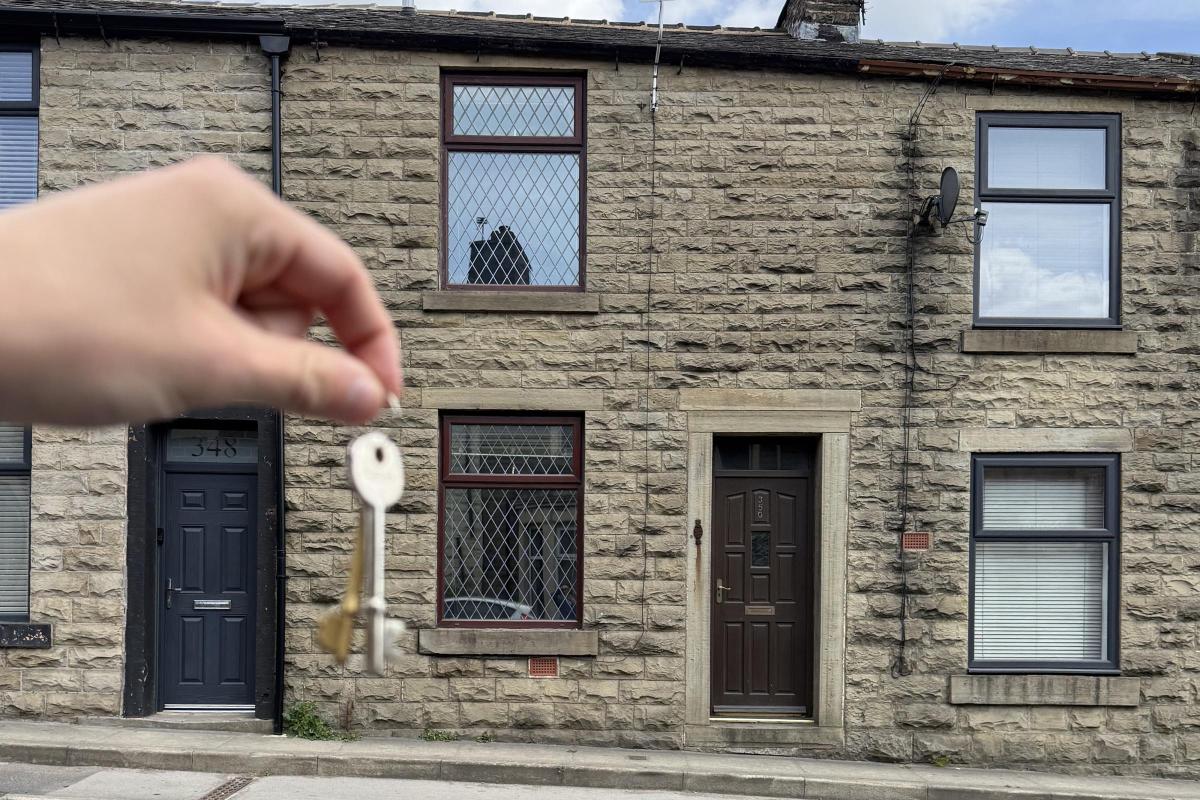

A man has bought his second property at just 24 years old by saving up at least £1,000 a month of his wages since the age of 18.
Jacob Waddington, 24, has always put away at least 50 per cent of his wages since leaving college, allowing him to purchase a £98,000 two-bed house at age 23.
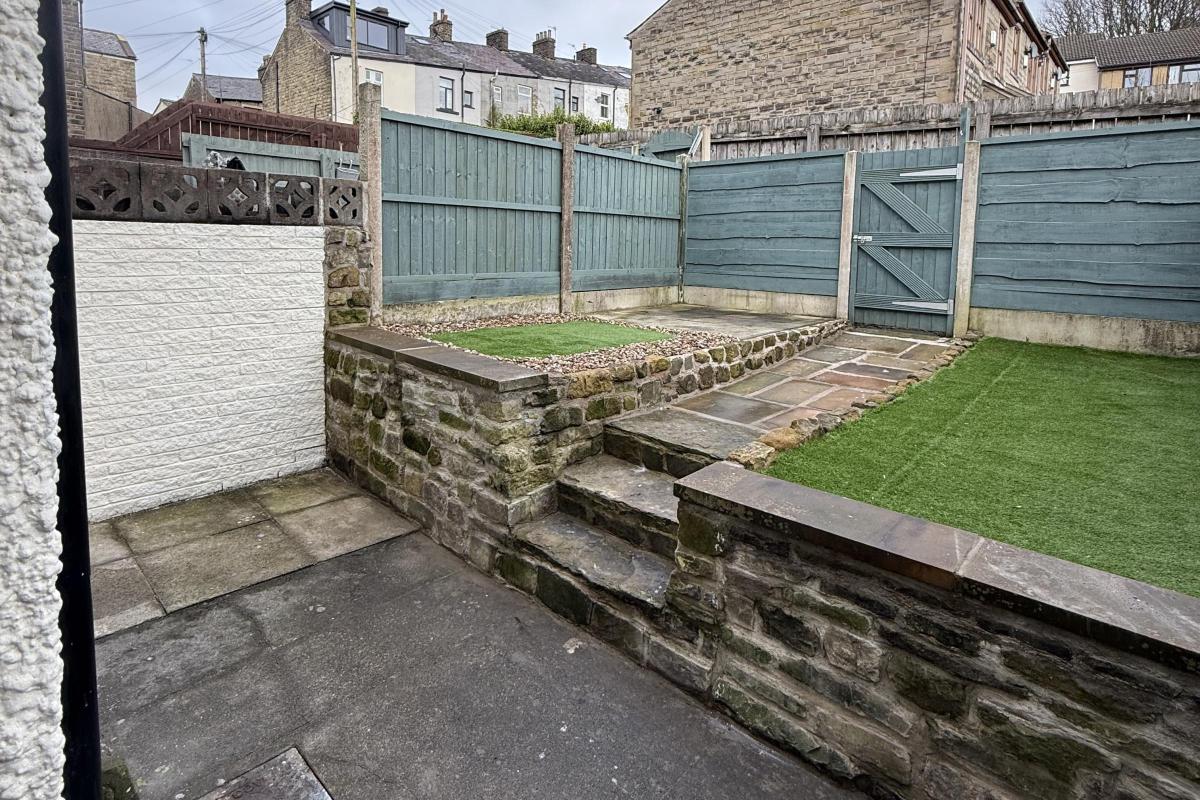
Alongside his girlfriend Holly, 23, Jacob, from Accrington, spent a year doing up the property before getting it valued at £160,000 and then renting it out.
They remortgaged the property and used the equity to purchase a second £140,000 cottage at auction and plan to turn this into an Airbnb.
Jacob said: “The plan is to maybe buy one more house to do up and sell, and then maybe buy a doer-upper to live in.

“All my friends and family say it’s amazing, and it does feel really rewarding.
“I’ve found a real passion for doing it, and I just feel really motivated to keep going.”
After leaving college at 18, Jacob started working for a telecoms company, earning £24,000 a year.
This felt like a big jump from the £6-an-hour job he had at JD Sports while still studying, so he found it quite easy to save a big chunk of his monthly wage.
As Jacob was still living at home and was paying just £200 a month to his parents, he was able to put £1,000 a month into a savings account.
His wages then went up to £33,000, meaning he was able to put away around £1,500 out of his £2,200 monthly salary.
In order to save such a large chunk of his wages, Jacob didn’t feel like he had to stick to a strict budget.
“I’d only really spend money on going out at the weekend, but you don’t need to spend loads on that”, he said.

“Me and my girlfriend would go for the odd meal out, but we love going on walks and things like that”.
In May 2025, Jacob and Holly discussed what they should use their savings for.
“We thought about buying a house together, but neither of us was desperate to move out, so we decided to buy a house to do up and then sell”, Jacob said.
Read more
-
Two arrested after police find 'rucksacks full of copper' following short pursuit
-
Ofsted praises Colne primary school's unifying 'peace walk' in strong report
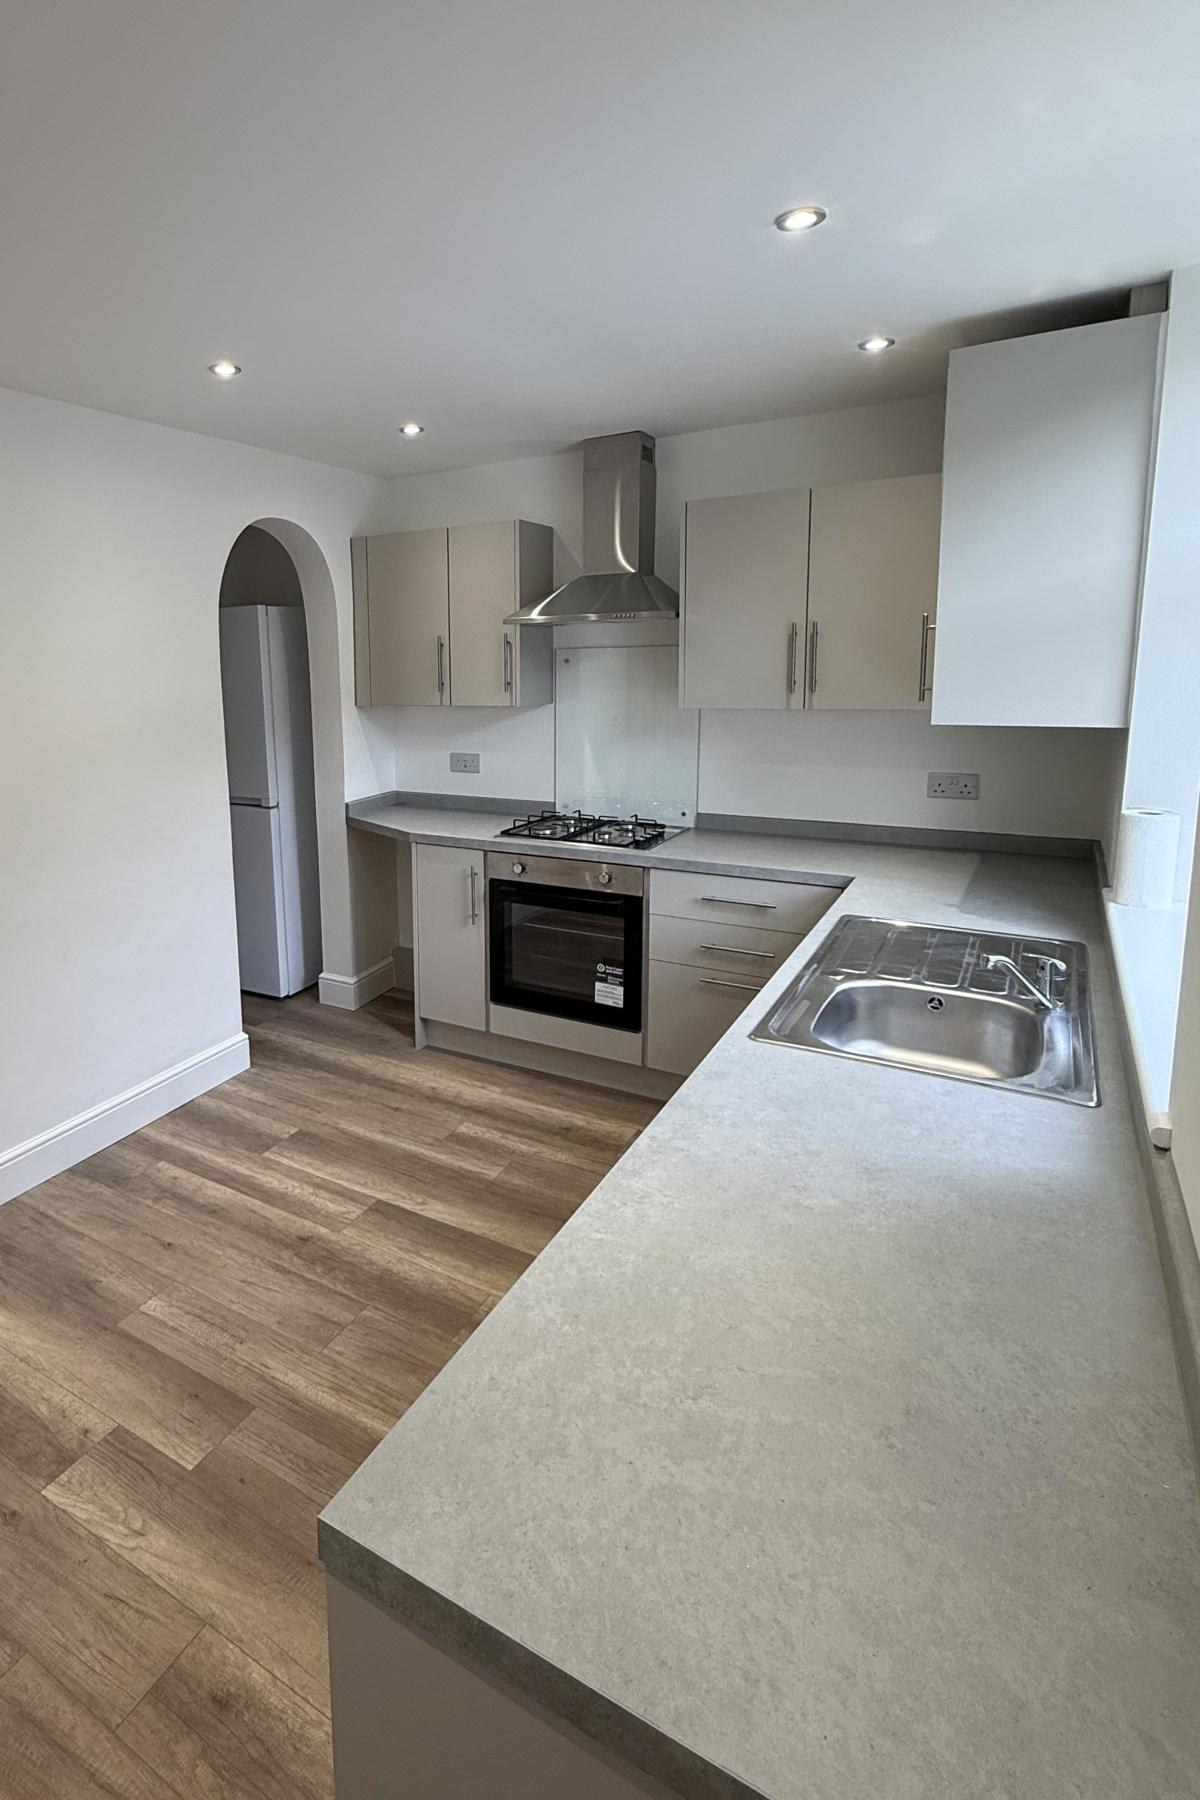
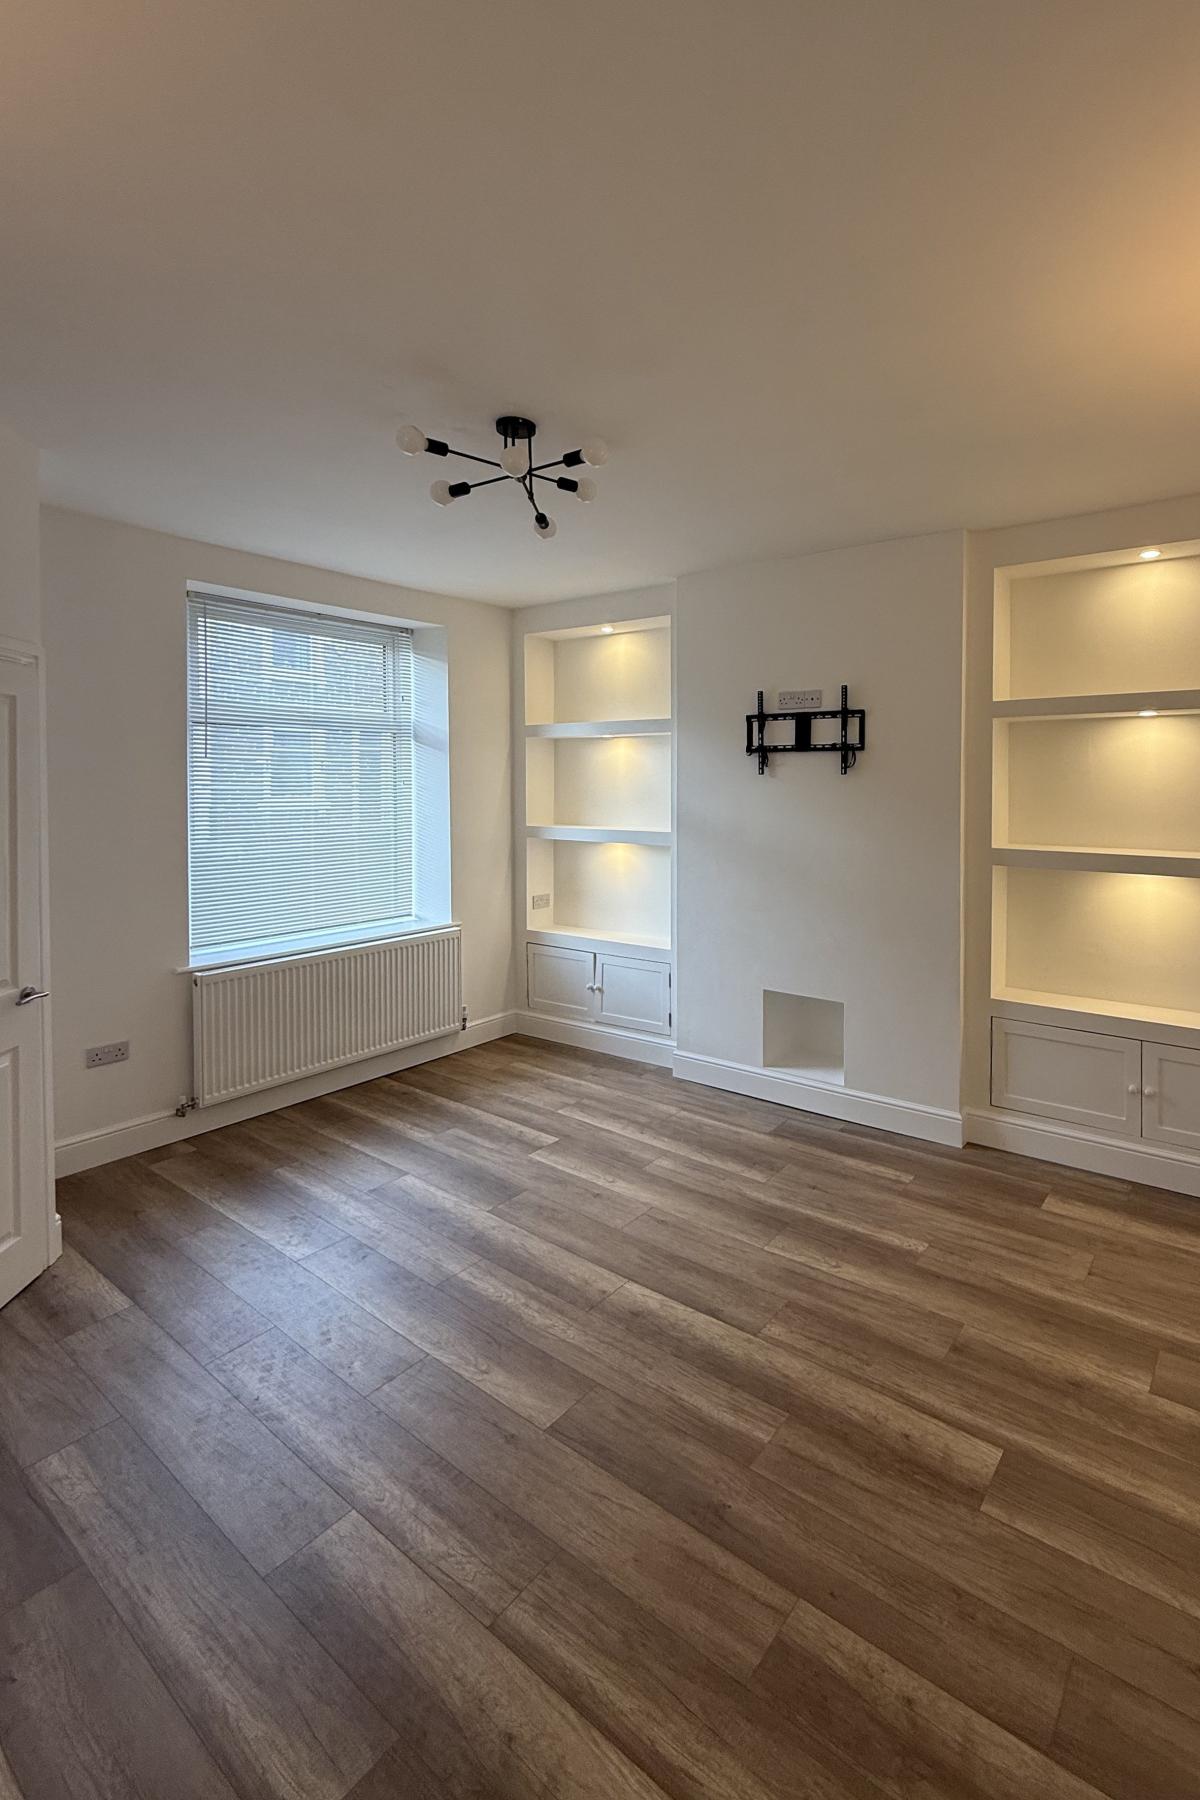
Together they put down a 25% deposit on a £98,000 two-bed terraced house and spent £20,000 on renovations.
Jacob left his job to work in a bar two days a week, earning £800 a month, and focused the rest of his time on the renovation project.
They put in a new kitchen, a new bathroom, re-plastered the walls, and installed a new boiler.
By January 2026, nine months after they purchased the property, the renovation was complete.
They then got the property valued again at £160,000 and withdrew the increase in value to their bank accounts by remortgaging the house.
After chatting to estate agents, they decided to rent out the property, instead of selling it, as demand was high for rented properties in their area.
In March 2026, tenants moved into the property, paying £875 in rent, more than double Jacob and Holly’s £430 a month mortgage.
They then began looking for a second property and found a 200-year-old one-bedroom cottage at the foot of Pendle Hill, famous for the Pendle witch trials.
“We’re thinking we might Airbnb this one out because it’s in a rural location”, Jacob said.
“It’s really picturesque and it’s in a historic area.
“It will be like a couple’s getaway.”
They used the money made from remortgaging their first property to put towards the £140,000 cottage and took out a 75 per cent bridging loan for 12 months on the rest of the property.
A bridging loan is a short-term loan where instead of paying monthly payments, you build up interest over a set period of time.
Jacob and Holly plan to spend a year doing up the property and estimate they will spend £30,000 on renovations.
They will then get it remortgaged, and use the money made from this to pay off the bridging loan, before moving on to a regular mortgage.
“The house next door has just sold for £320,000 for a two-bed, so I’m hoping to get this one remortgaged at around £250,000”, he said.

“If we can do that, we’d be able to pull out more money than we put in, because it will have increased in value by so much”.
Jacob has calculated that if he rents the Airbnb out at £120 a night at a 60% occupancy, he will make £2,000 a month.
After paying council tax, bills and the £650 mortgage, he will then have around £1,000 leftover.
“It could be more profitable than the standard rental”, he said.
Jacob plans to buy another property to sell or rent out after this one, before purchasing a home to live in with Holly.
He said: “If someone wants to buy a house, whether to live in or to sell, don’t be afraid to buy something that needs a little work done to it.
“If you buy something a bit more run-down, you can get much bigger returns on it, as it will have increased in value.”

Share